Verify customers, monitor activity and manage risk with identity, screening, monitoring, fraud, and authentication controls configured around your payment program.
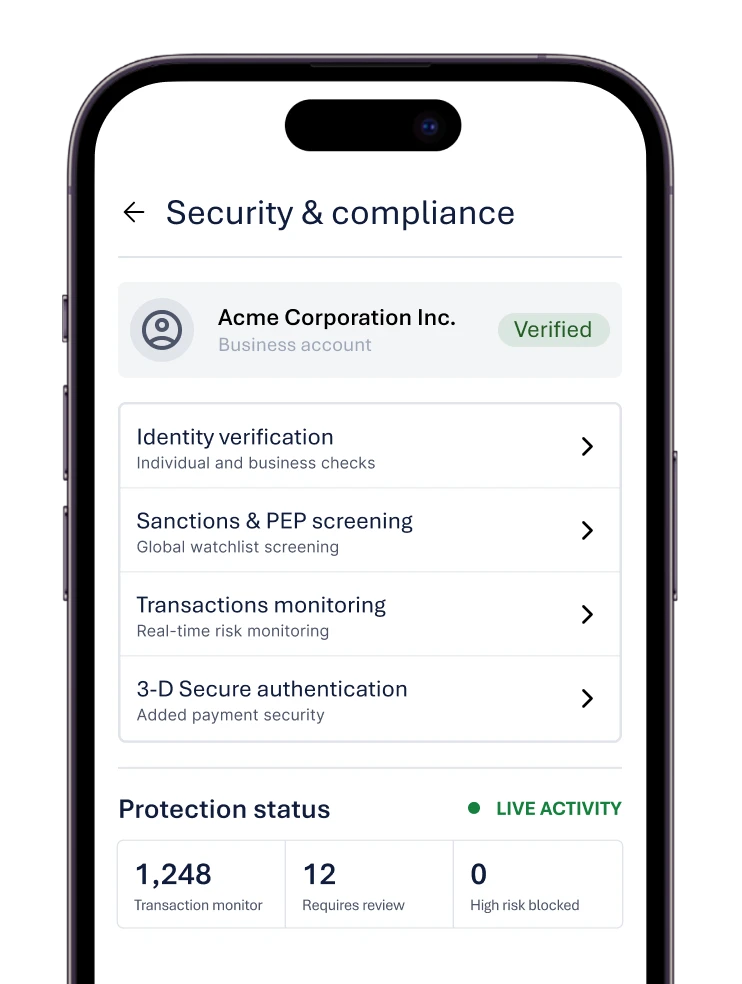
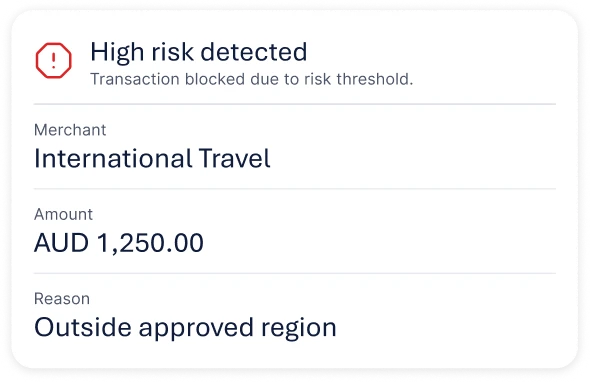
Protection at scale on regulated, scheme certified infrastructure.


Apply the right identity, screening, monitoring and authentication controls based on your program, product and markets you operate in.

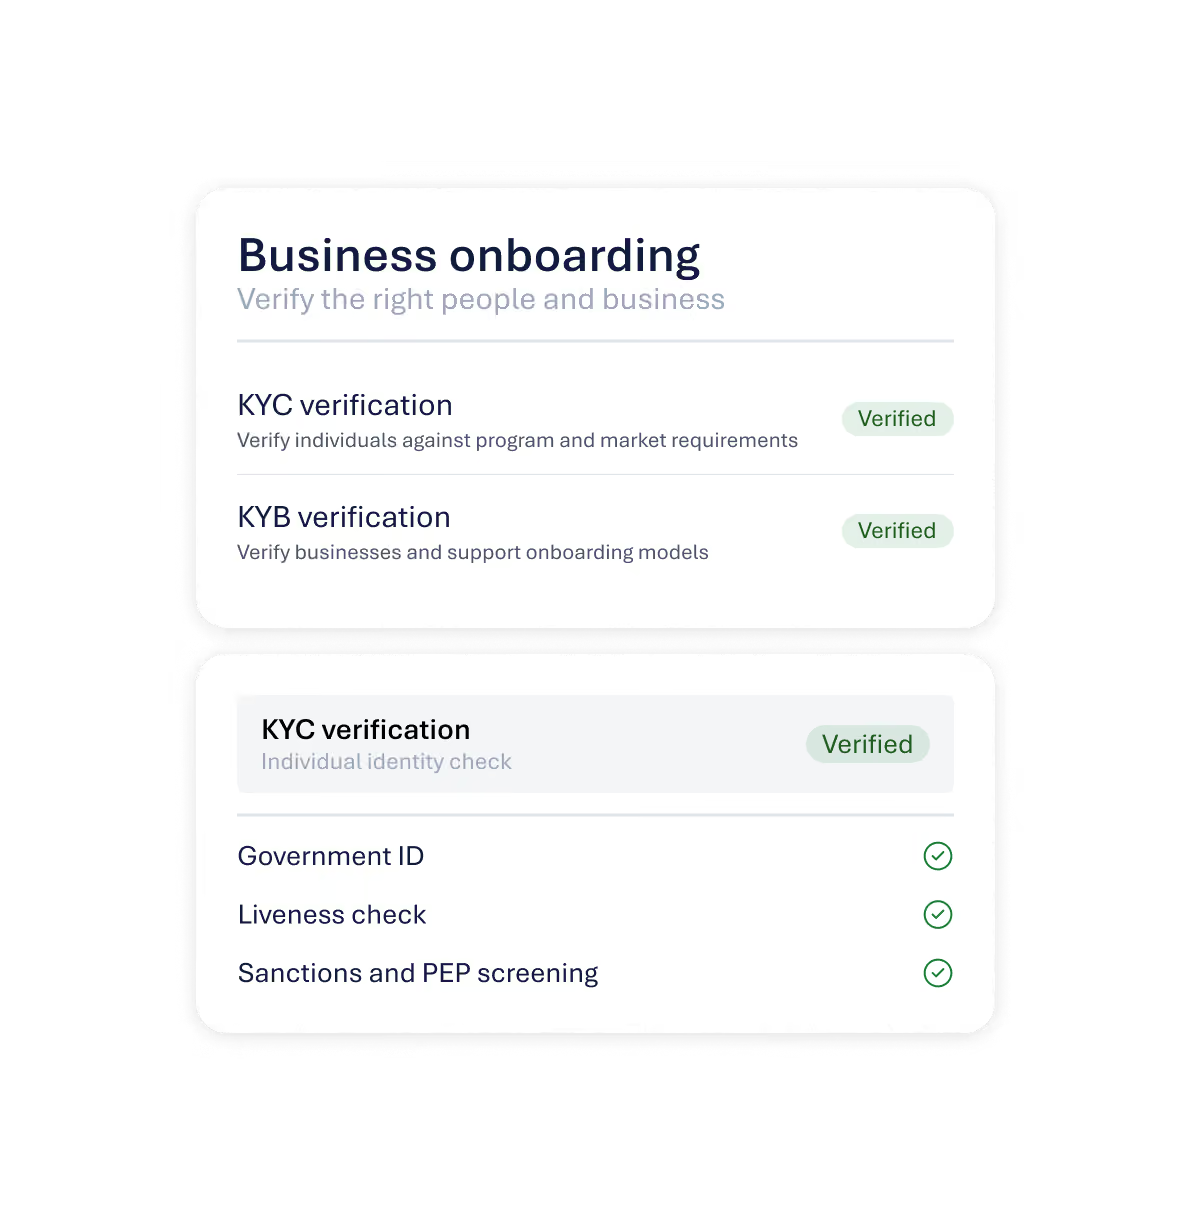
Verify individuals and businesses using checks appropriate to the program and market.

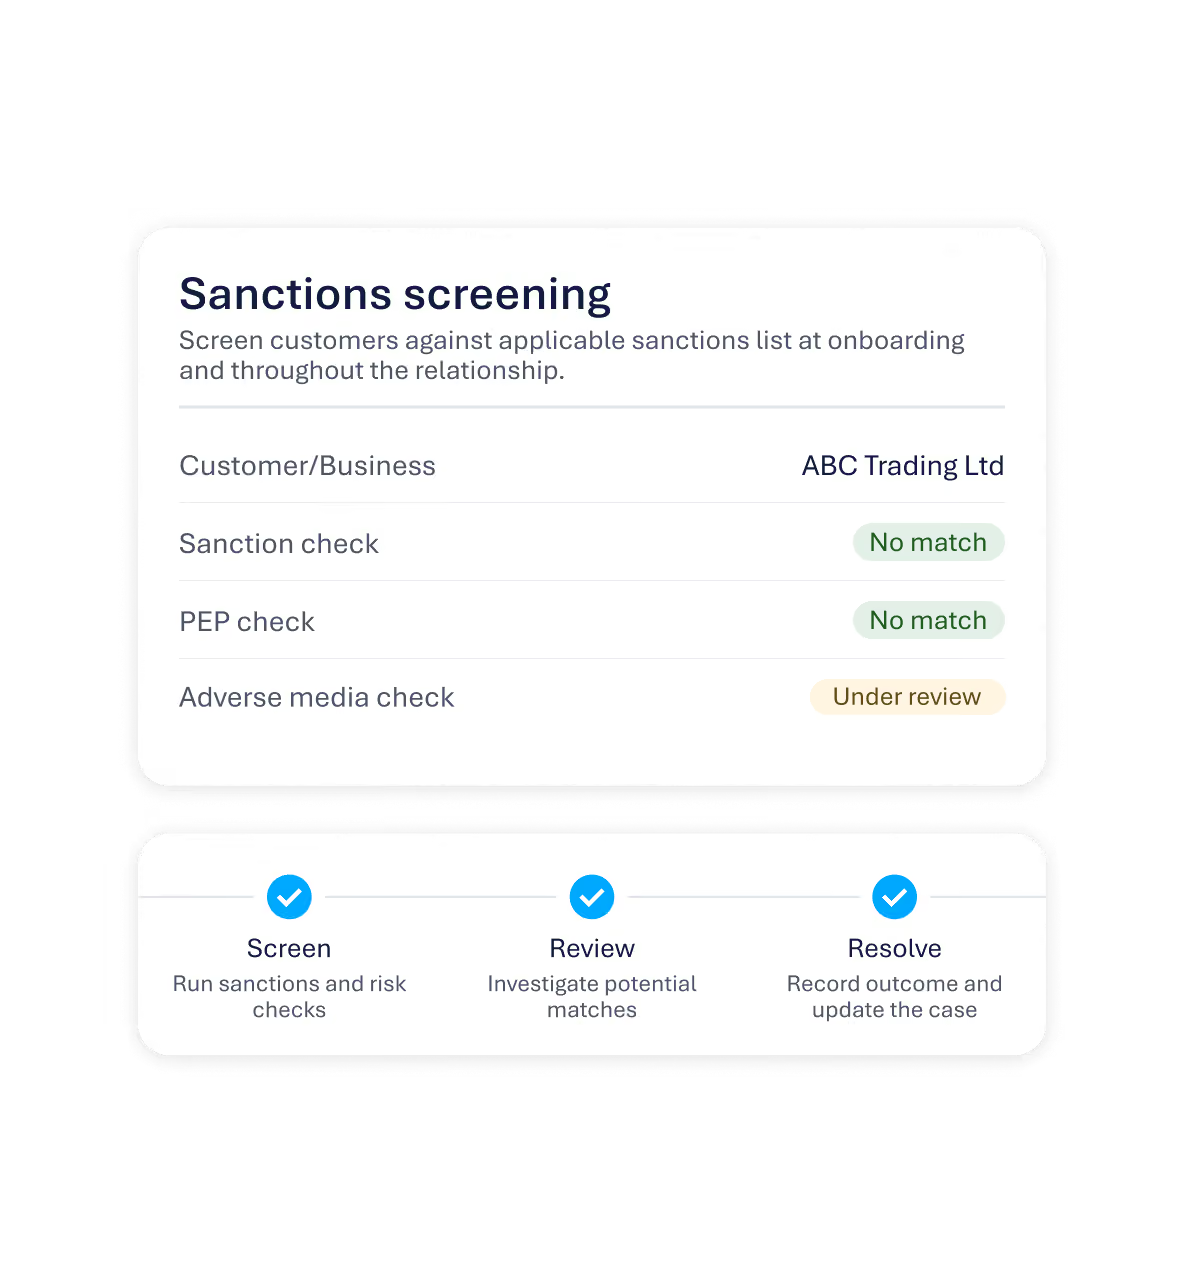
Screen customers against applicable sanctions, PEP, and adverse media sources during onboarding and on an ongoing basis, in accordance with the requirements of the program and market.

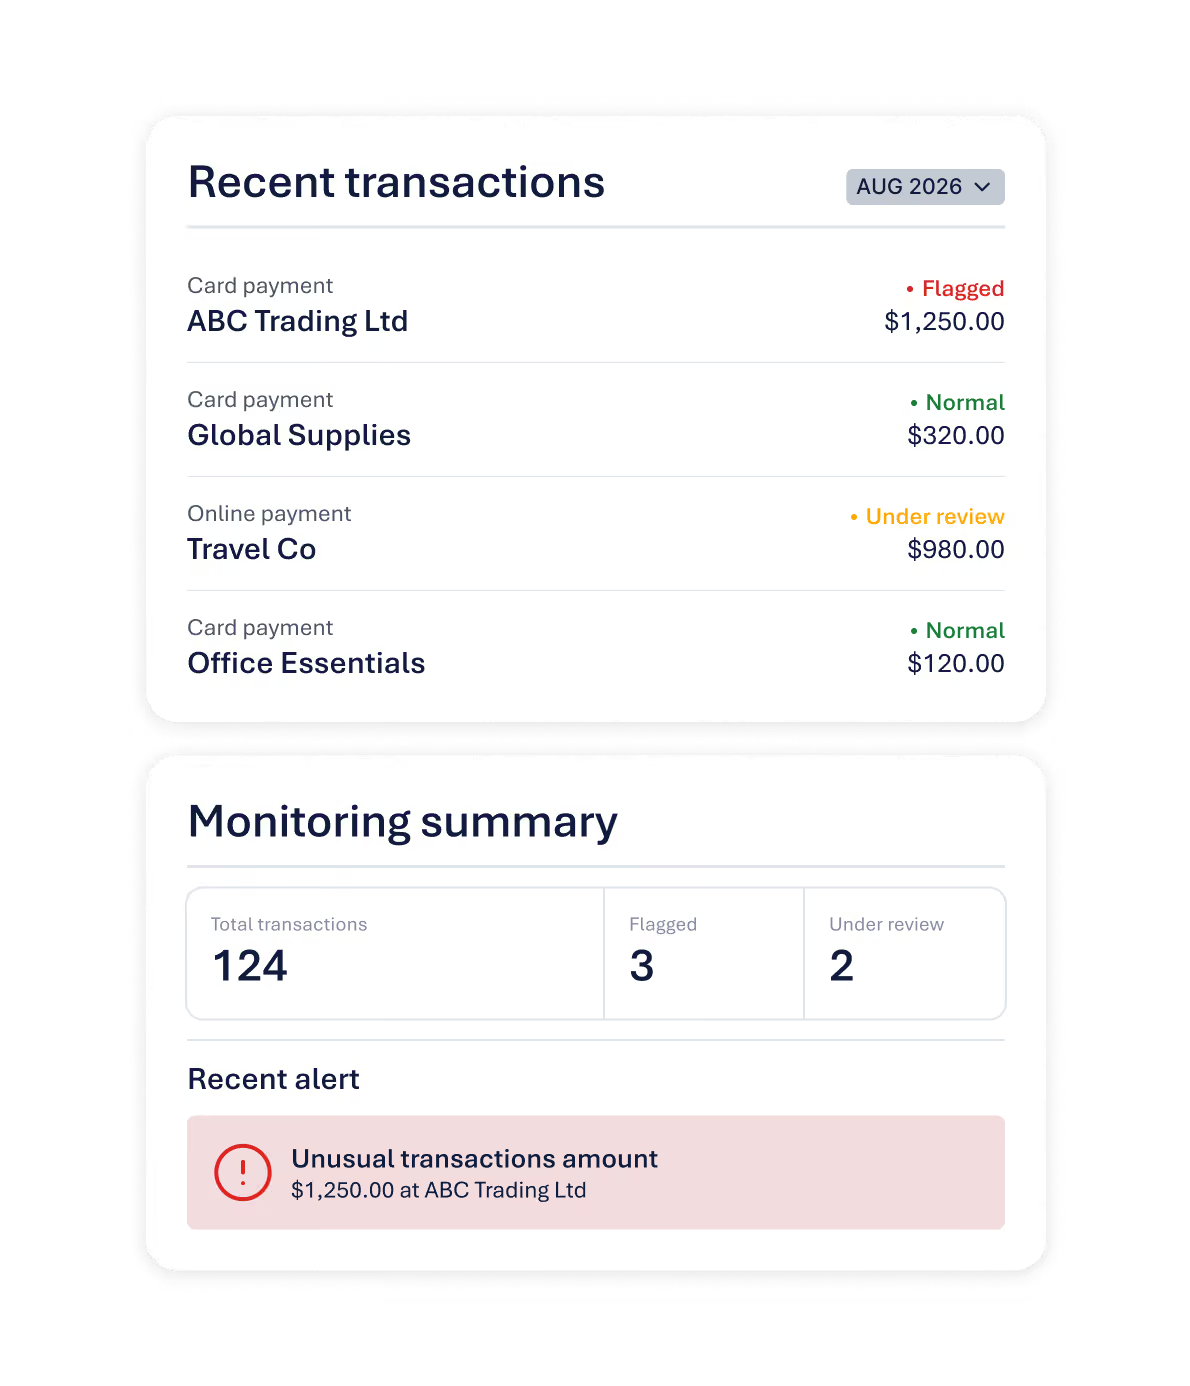
Monitor transactions and activity against the rules, risk thresholds and controls configured for your program.

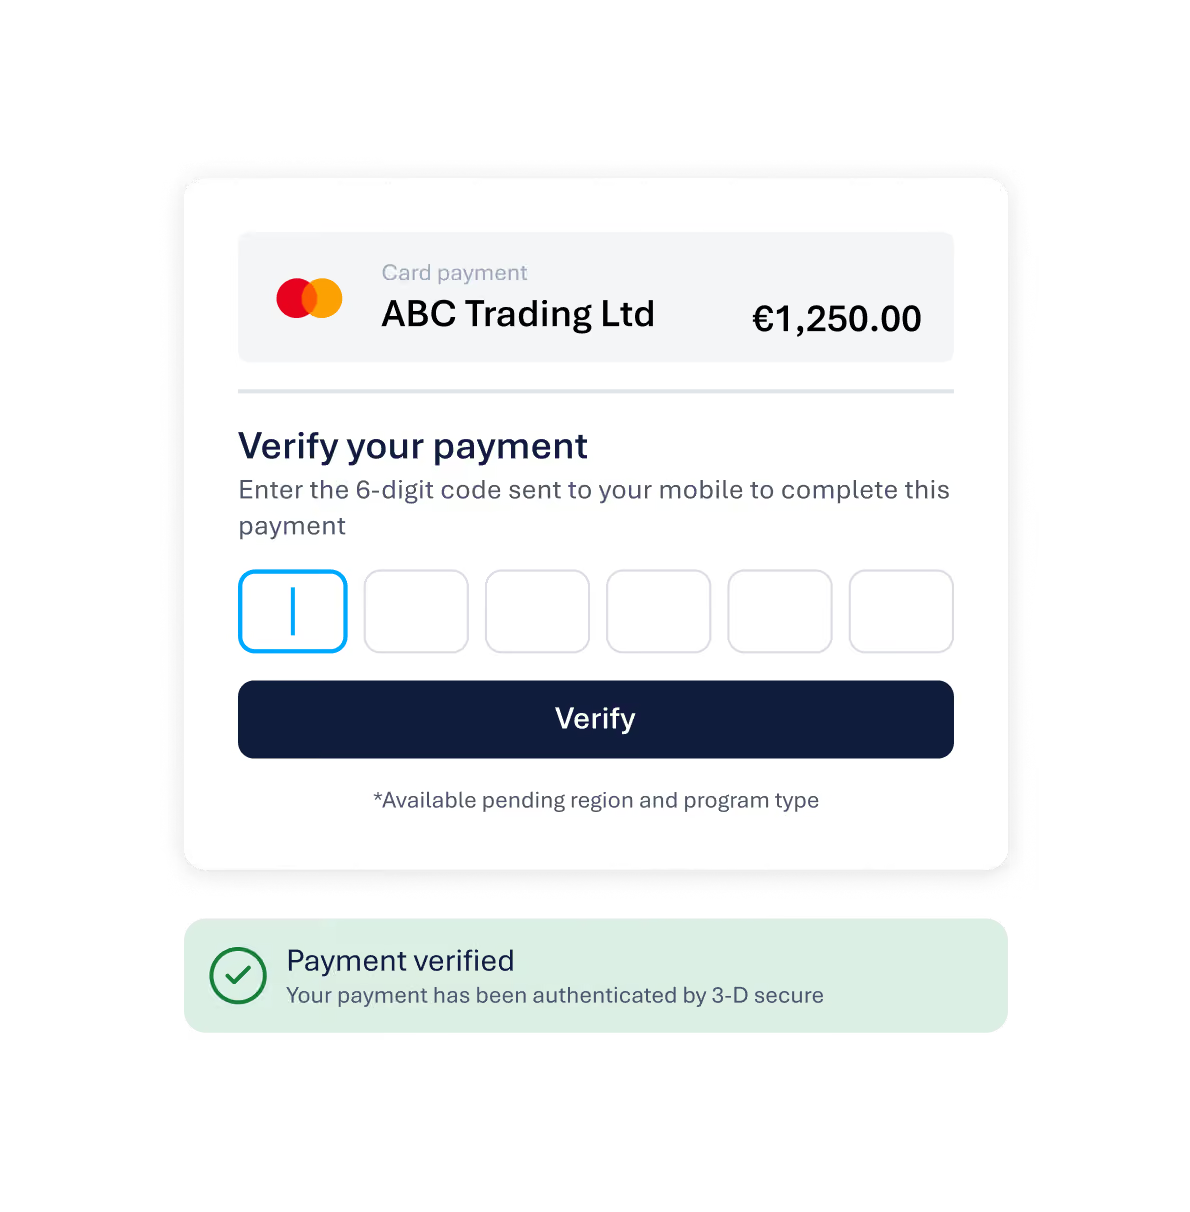
Apply authentication in line with scheme, program and regional requirements.

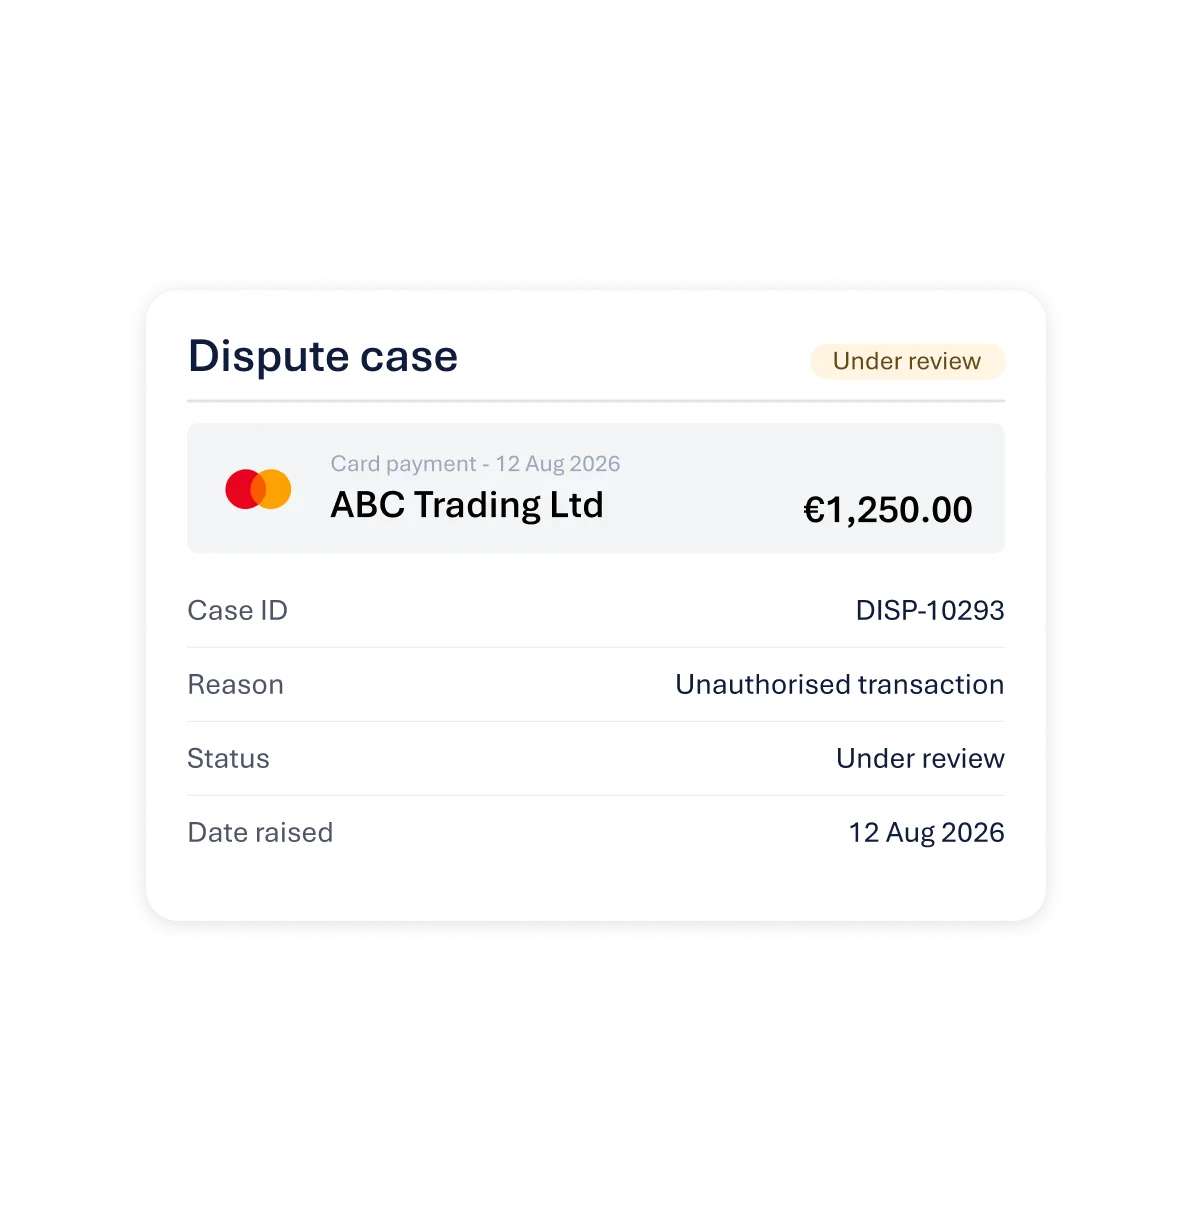
Manage disputes through structured workflows for case handling, evidence and scheme processes.

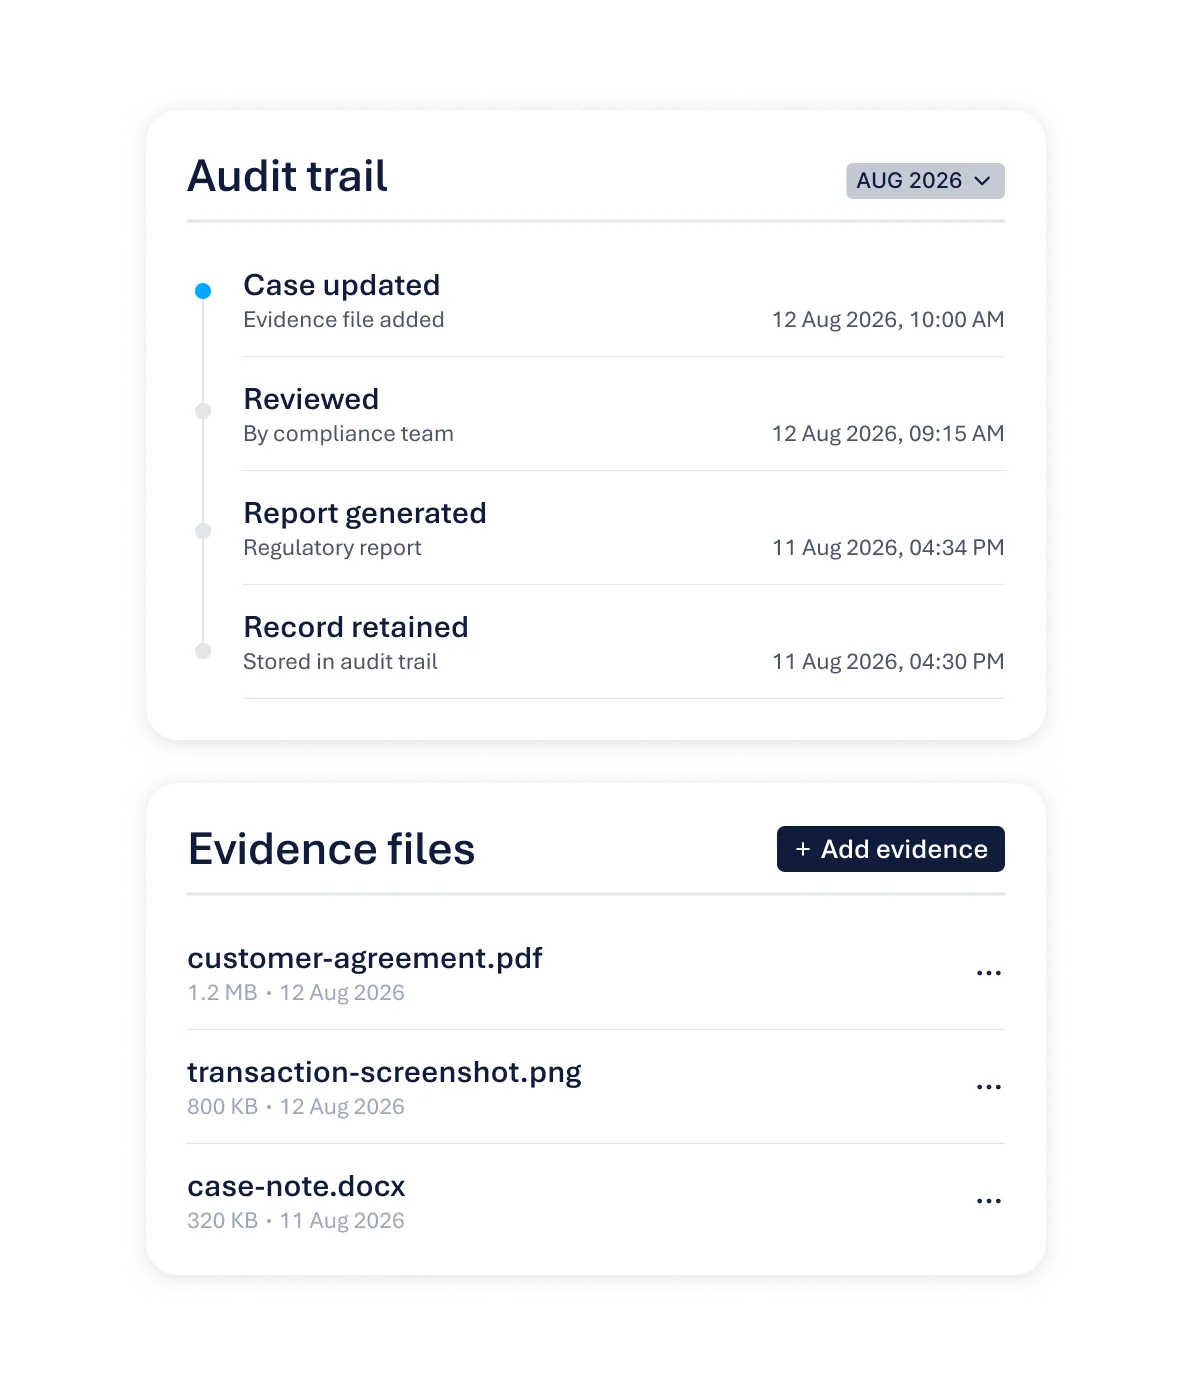
Maintain records and reporting outputs to support program oversight, audits and regulatory requirements.
Bring together onboarding, screening, monitoring, authentication and dispute management based on the needs of your program and market.
Contact salesConfigure onboarding checks tailored to the program, product and market to meet compliance, legal and market standards.
Screen customers against applicable sanctions, PEP and adverse media sources, with workflows for reviewing potential matches.
Evaluate transactions and activity against the thresholds and controls configured for each program.
Protect digital payments and account access using authentication appropriate to the market, scheme and customer journey.
Run disputes and chargebacks through structured workflows with clear ownership, evidence management and case visibility.
Keep the records, reporting and operational evidence needed to demonstrate how program controls are working.
EML Payments gives you flexible ways to launch, integrate and modernise payment programs, with the tools and support to match where you are today.
Choose how you connect. Start with ready-made white label portals and components or integrate directly through APIs and webhooks.
Move onto EML with less disruption. We assess what you have, plan the pathway, and support the migration and the operations that follow.
Set identity, screening, monitoring and authentication requirements around the product, market and risk profile.
Run appropriate KYC or KYB checks during onboarding, with sanctions, PEP and adverse media screening before access is approved.
Set transaction thresholds, behavioural rules, alert conditions and authentication requirements.
Monitor transactions and activity against configured controls throughout the program lifecycle, applying authentication and monitoring requirements where applicable.
Route alerts, screening matches, disputes and chargebacks into structured workflows with clear ownership and supporting evidence.
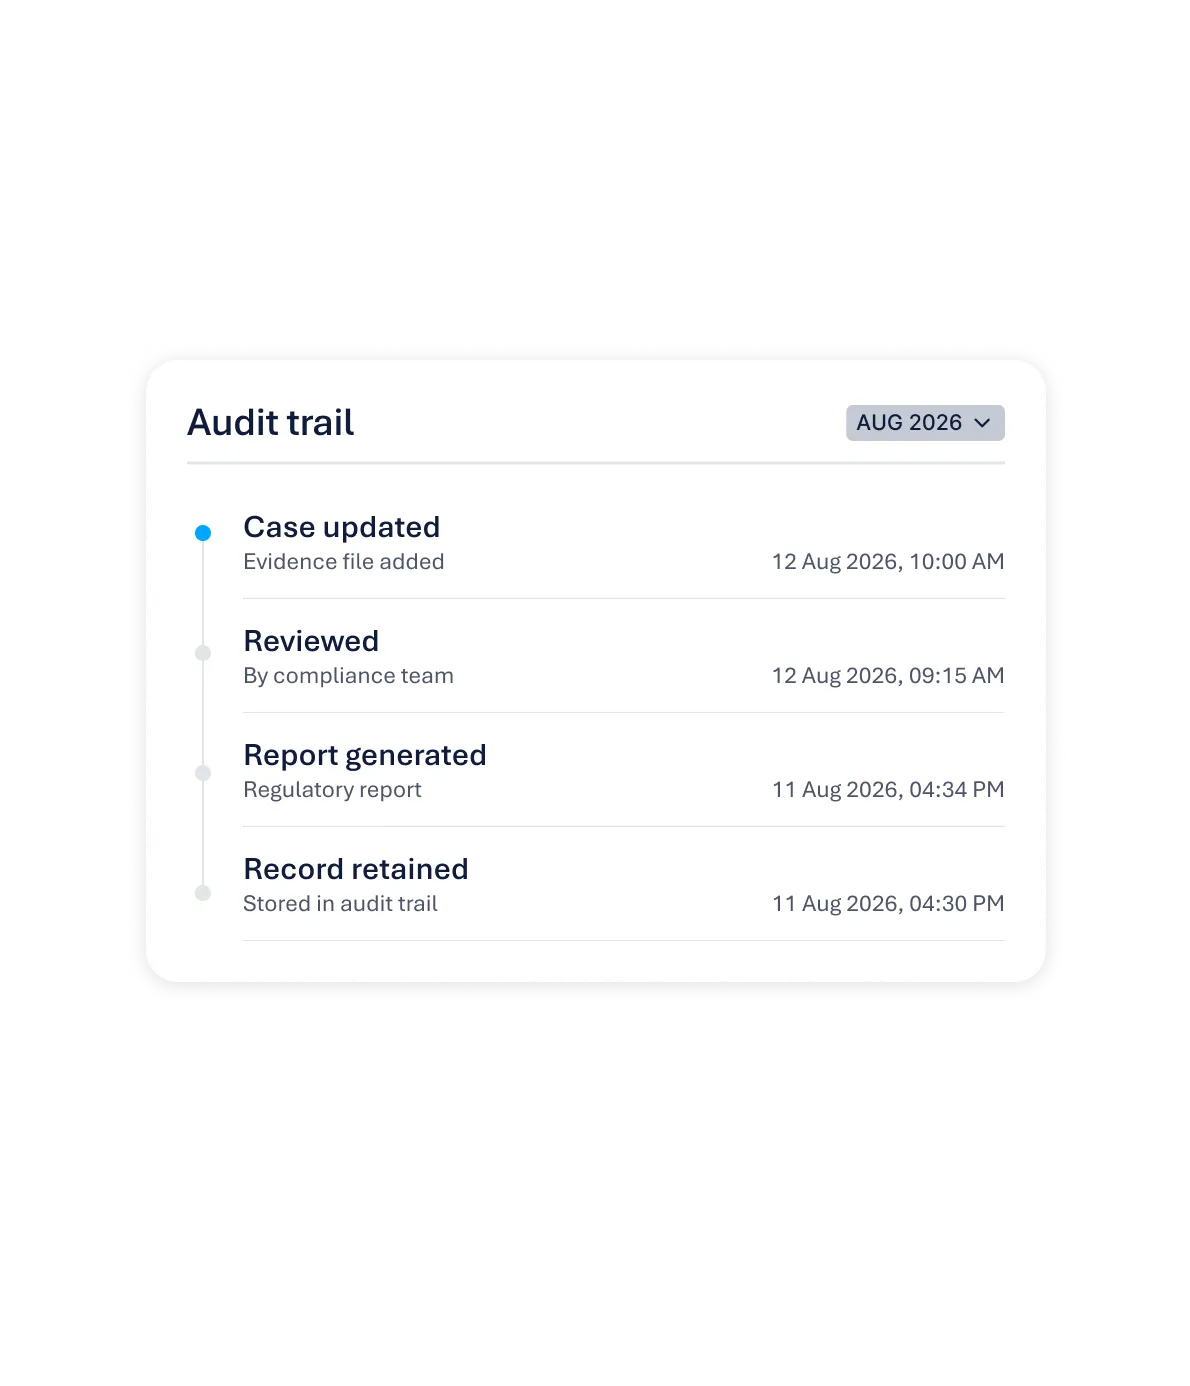
Maintain records of checks, alerts, decisions and cases to support oversight, audits and regulatory requirements.
Across five sectors, EML combines configurable technology, regulatory know-how, proven expertise and end-to-end capability to solve complex payment challenges.

For employers and benefits providers managing pay, expenses, rewards and entitlements for their people.
Salary packaging
Employee rewards
Earned wage access
Expense management

For central and local government teams disbursing funds to people who need them.
Disability payments
Benefits and allowances
Carer disbursements
Emergency and crisis relief
Managed funds

For businesses moving money at scale, deliver funds quickly through flexible, branded payment experiences with built-in controls and limits.
B2B payouts
B2C payouts
Corporate incentives
Lending and credit

For brands, retailers and venues managing gift, loyalty and event programs. Create branded value customers can buy, receive and spend wherever you operate.
Gift cards
Stadiums and events
VIP programs
Loyalty and rewards
Cashback and promotions

For fleet teams managing spend beyond the pump. Fuel, EV charging and everyday mobility spend on one open-loop card.
Fleet & Fuel Expenses
*Use cases vary per region, contact Sales for more information.
United Kingdom: FCA authorised e-money licence. Ireland and Europe: Central Bank of Ireland authorised e-money licence, passported across the EU. Australia: Australian Financial Services Licence. North America: we work through issuing bank partners rather than holding our own licence, which is the standard model in that market.
Program funds are safeguarded under the arrangements that apply in each market, which differ by licence and by banking partner. We provide the detail your procurement and risk teams need as part of scoping.
Responsibility depends on the program and operating model. Fraud controls, monitoring, investigation and escalation responsibilities are defined during program design and agreed before launch. Where EML performs issuer, processing or financial crime functions, the applicable responsibilities are reflected in the program's operating model and contractual arrangements.
No, and they shouldn’t. Identity, verification and screening requirements are determined by the product, customer, program structure, jurisdiction and applicable regulatory requirements. We agree the appropriate approach during program scoping.
Authentication is applied to meet scheme and regulatory requirements in each market, with step up used where the risk warrants it rather than applied uniformly. The aim is to meet the requirement without putting friction in front of customers who do not need it.
Disputes and chargebacks run through structured workflows with evidence handling and scheme submission. Scope depends on the schemes and dispute types in your program, which we confirm during scoping.
Audit trails, monitoring artefacts and reporting outputs are produced from the record of what actually happened. Reporting to your own regulator remains your obligation, and we support it with the evidence.
Yes. Interfaces are built with accessibility and multilingual support, and controls can be tailored to a person's circumstances, so support is delivered safely without removing their independence. This matters most in government and social programs, where the recipient did not choose to be in the program.
One partner with the card issuing and processor platform, the licence and the people to launch your program and keep it running as it scales.

Cards, accounts, wallets, money movement, controls and data brought together and configured around your program.

APIs, pre-built components, white label portals and partner integrations. Connect in the way that works for your team.

Issuer, processor and program manager capability in one place, with the licensed infrastructure to run complex and regulated programs end to end.

Security, access controls, data protection, fraud monitoring and sanctions screening protect your program, your users and your money, informed by local regulatory environments.

Live across APAC, Europe, the UK and North America, with teams who understand local rules, schemes and market realities based on decades of experience.
Real experts alongside the technology, from pilot through to live operation. You get a partner, not a ticket number.
Issue, process and project manage cards ad accounts. Move money and manage complex payment flows with real-time intelligence and control, with proven experts behind every transaction.
Create accounts, cards and wallets at scale.
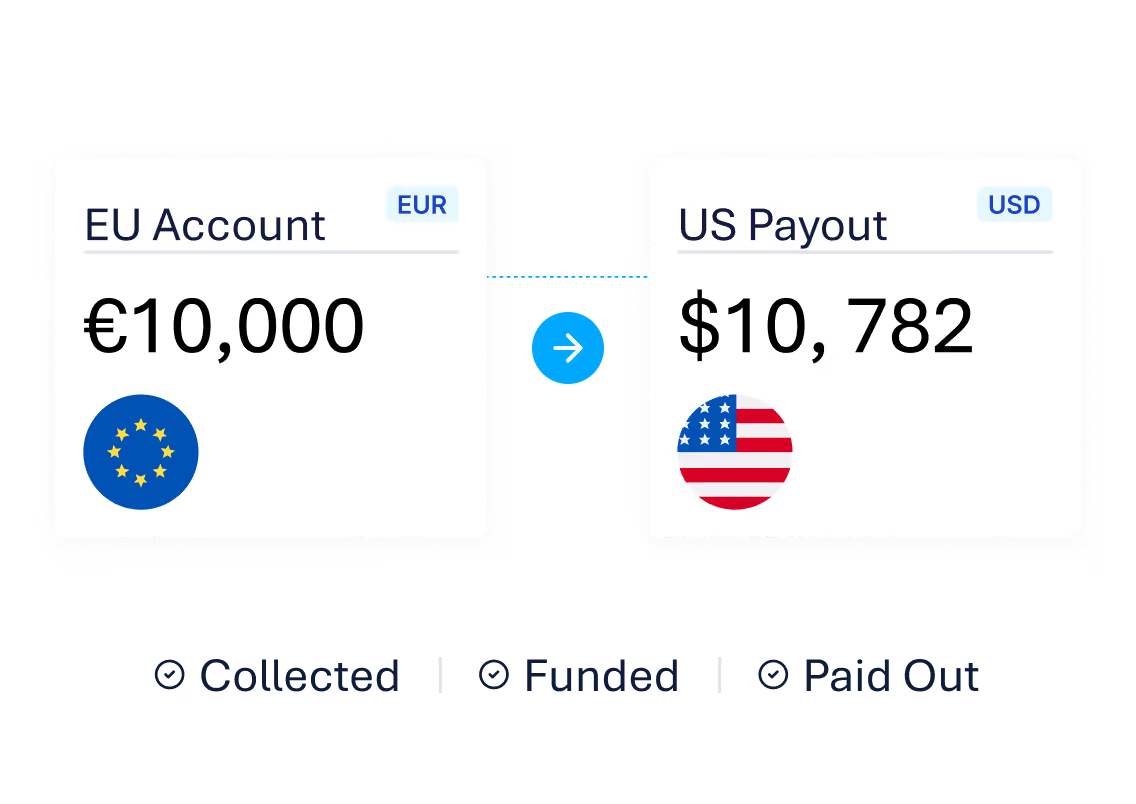
Move money in and out of your program.
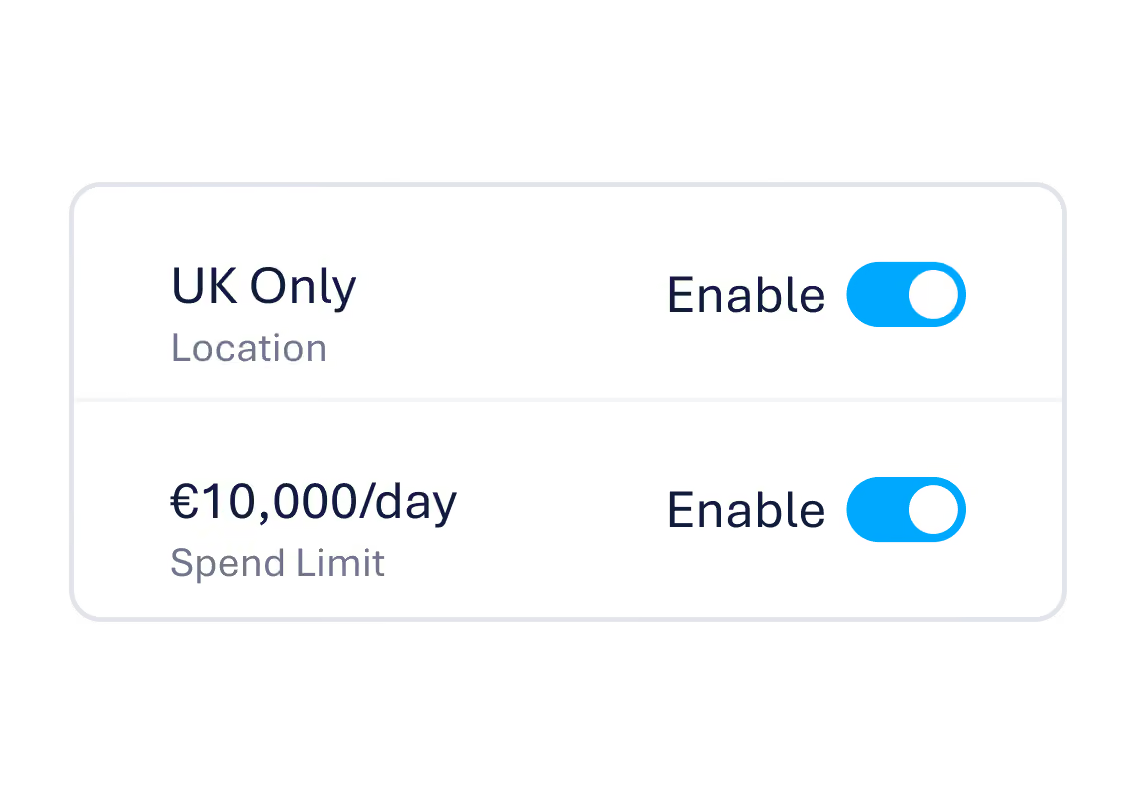
Shape how money behaves in real time.
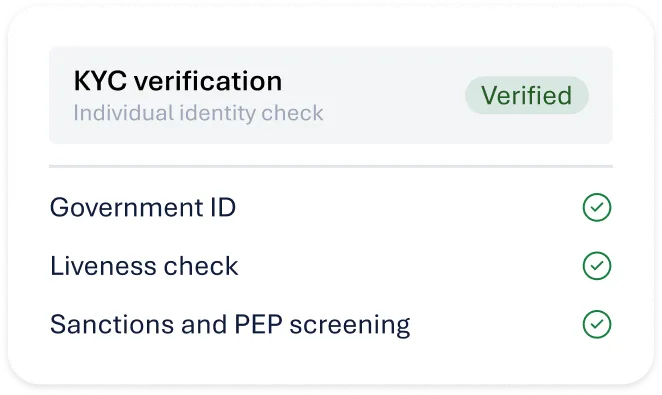
Build trust and protection into every transaction.
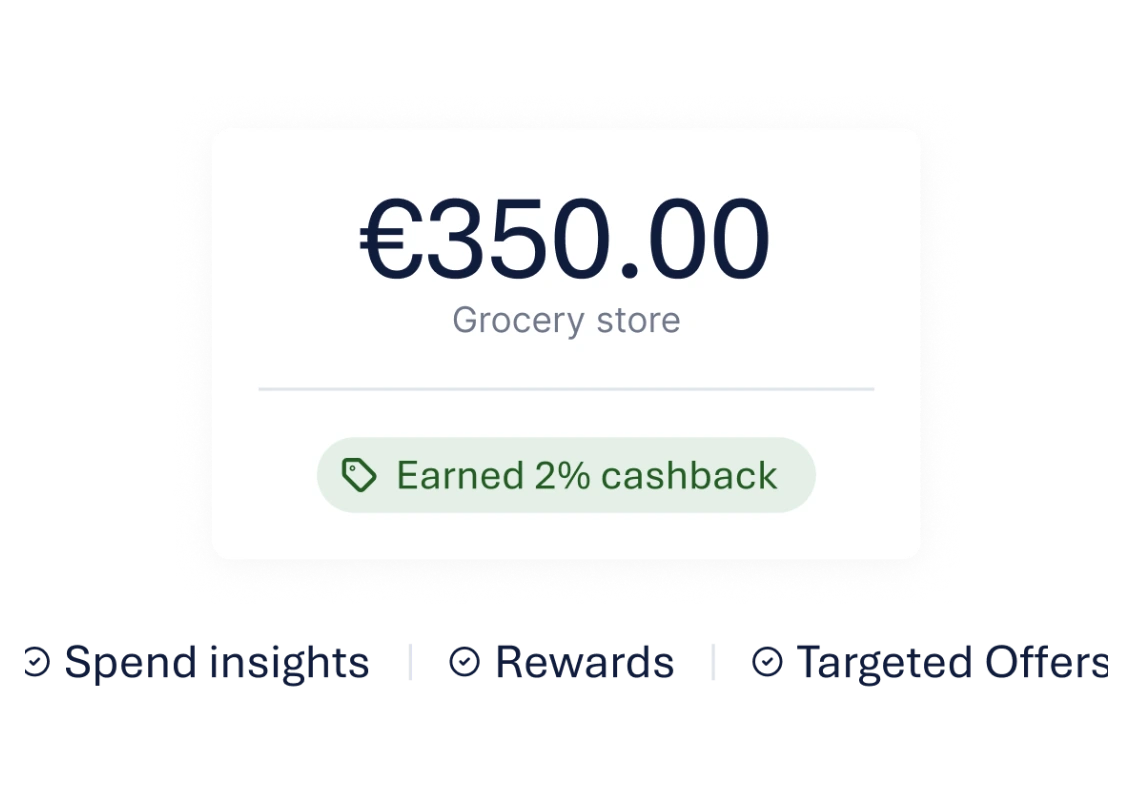
Use insights and incentives to drive growth.
Build with white label portals, pre-built components or direct integration.
Whether you're launching, modernising or scaling, an EML specialist will map the right platform, operating model and next steps to get you there. Let's talk.