Fund card programs and make payouts to customers, employees, suppliers and beneficiaries through cards and supported bank payment methods.
Move money at scale on regulated, scheme certified infrastructure.


Choose how funds enter your program, how recipients are paid and how payment activity is tracked. Available methods depend on the market and program.
Make funds available for cardholders to use within the controls defined for the program.

Deliver payments to customers, employees, suppliers, claimants or beneficiaries through cards and supported bank payment methods.

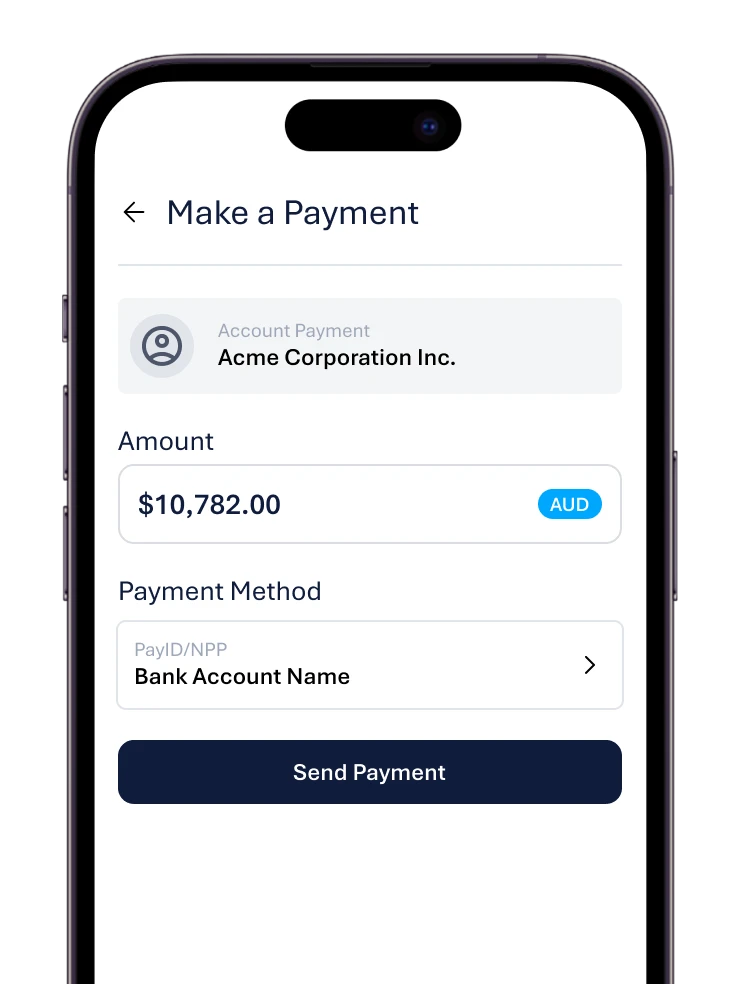
Initiate an individual payment, process a scheduled batch or trigger a payment from an approved program event.

Monitor payment instructions and identify payments that have completed, failed or been returned.

Use the payment methods available for the relevant EML Payments platform, market and program.
Let's talk about how EML can help you deliver better outcomes, at scale.
Bring funds in, move them out and keep settlement, reconciliation and finance operations under control.
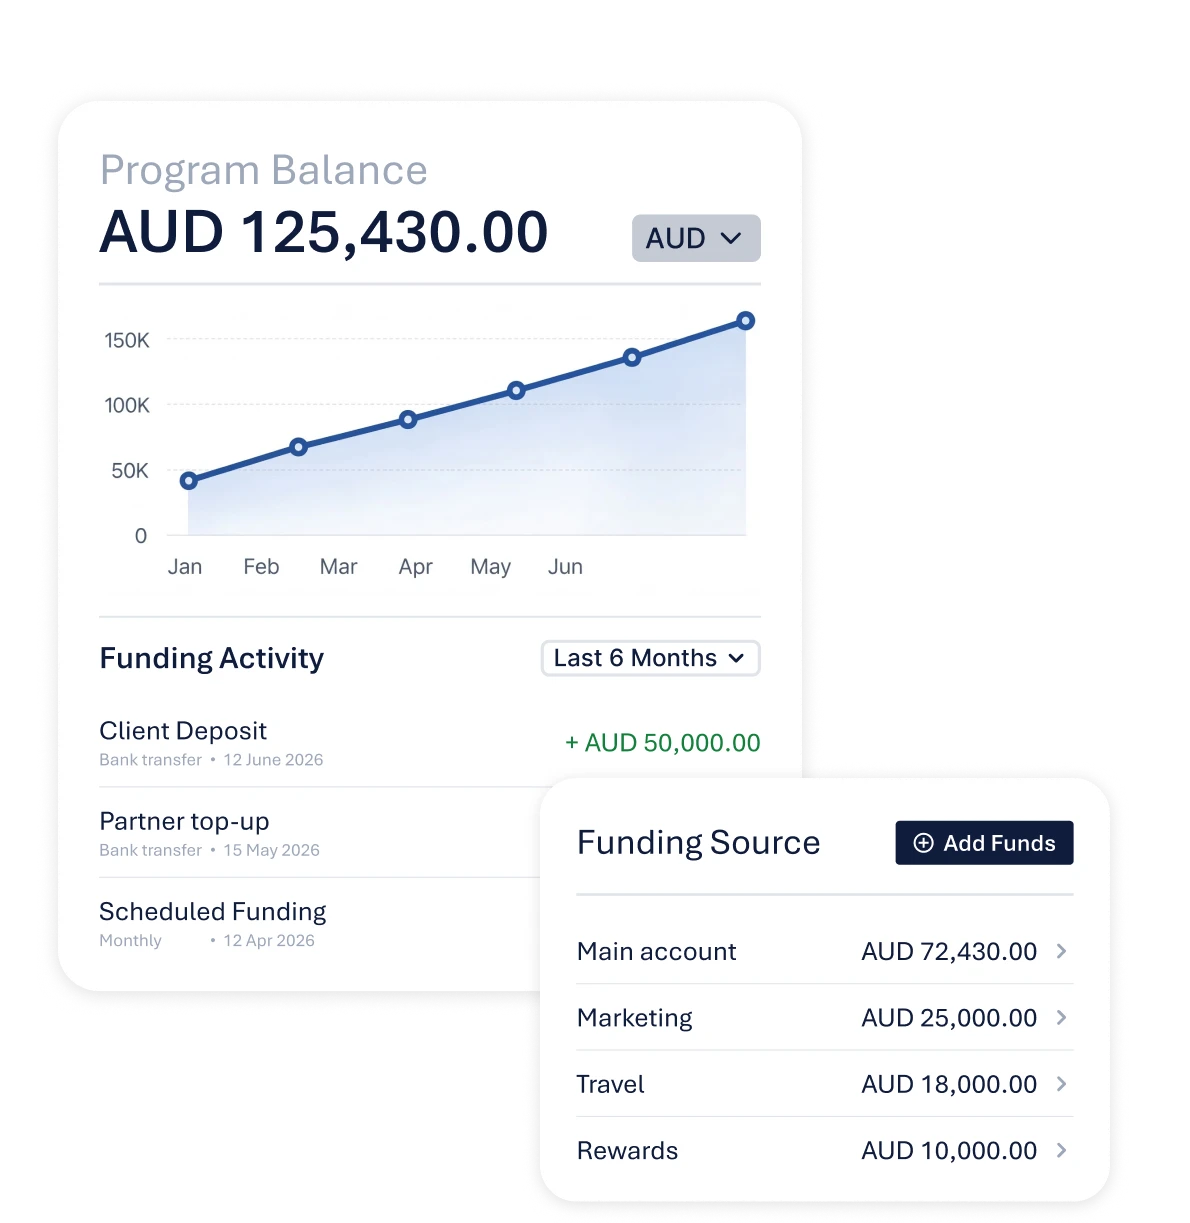
Contact salesBring funds into your program and allocate them to the appropriate card, account or program balance.
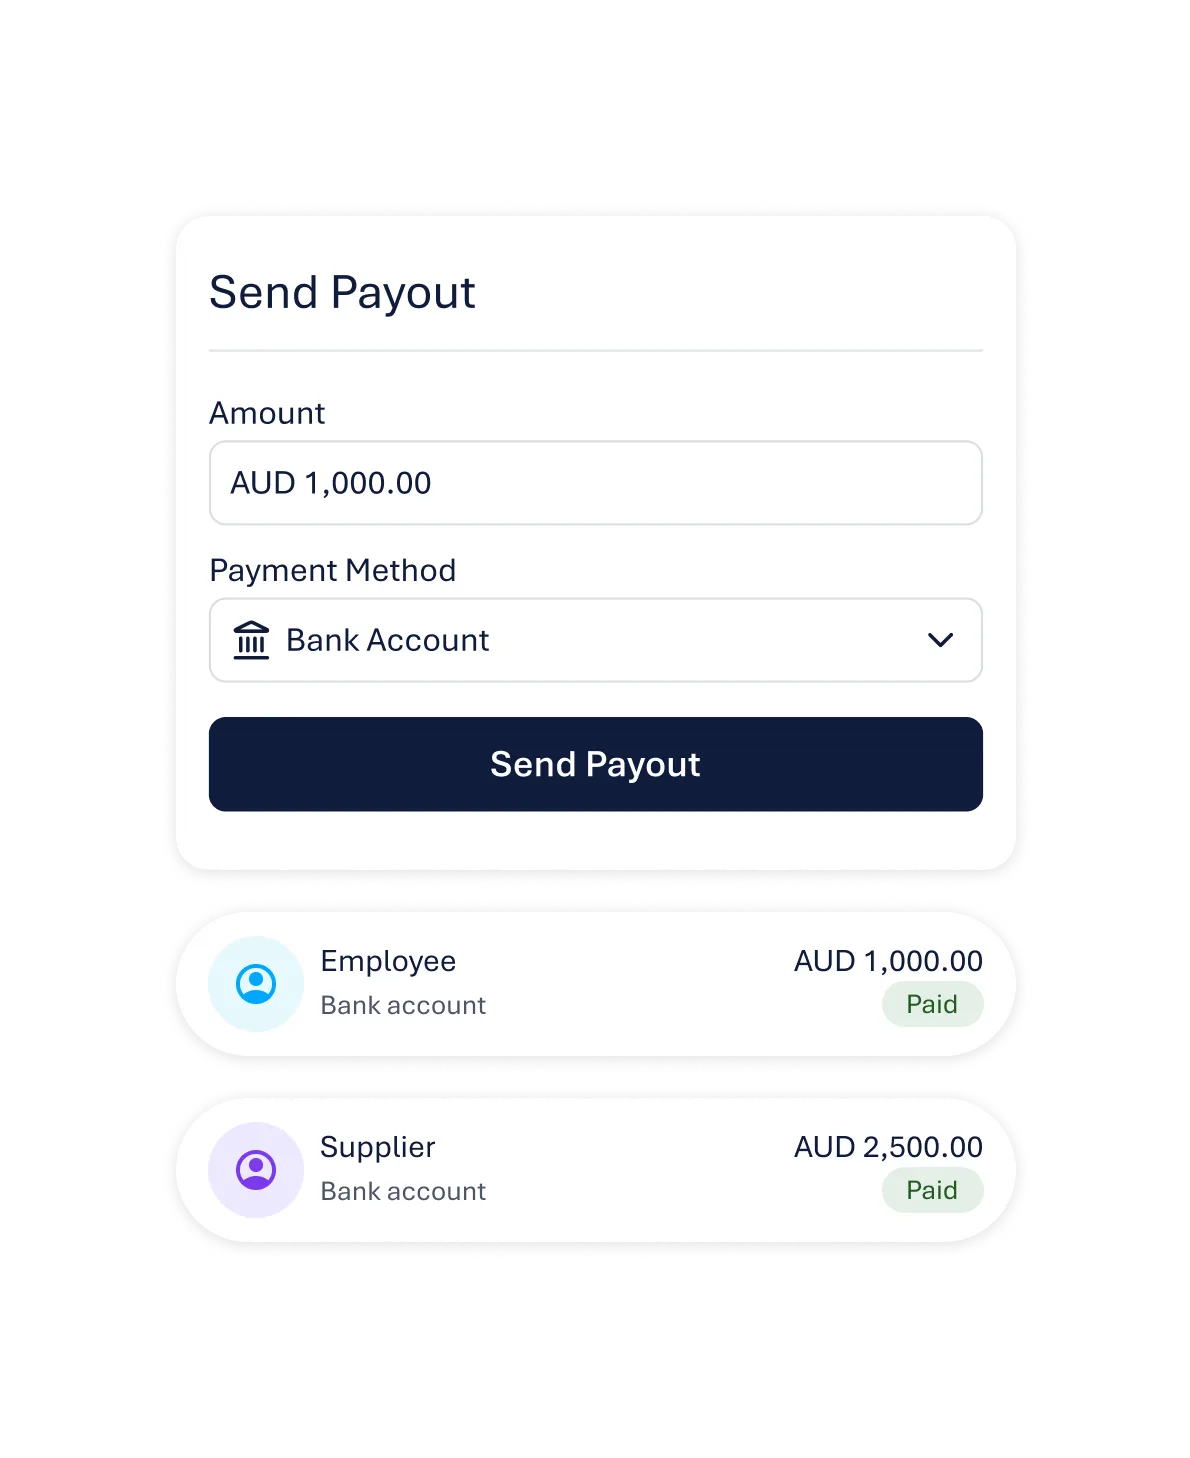
Pay employees, customers, suppliers, claimants and beneficiaries through cards, internal accounts or supported bank rails.
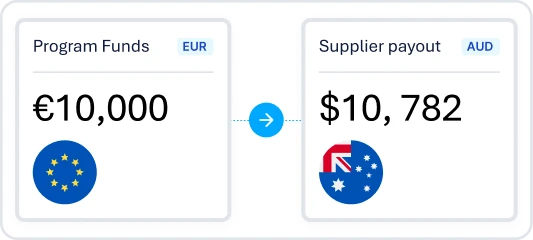
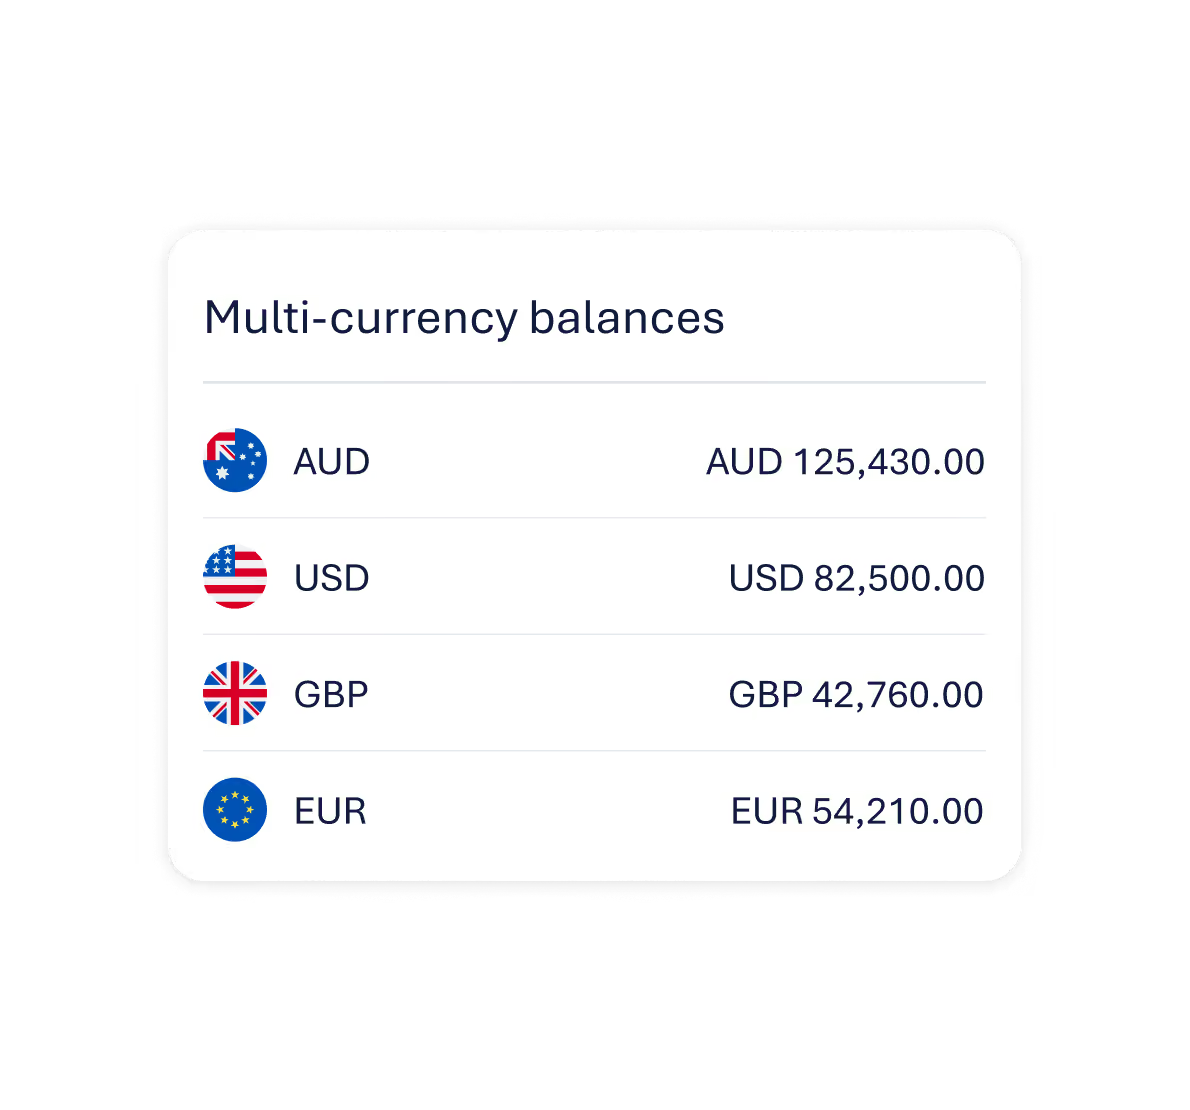
Hold balances, move value and report consistently across supported currencies.
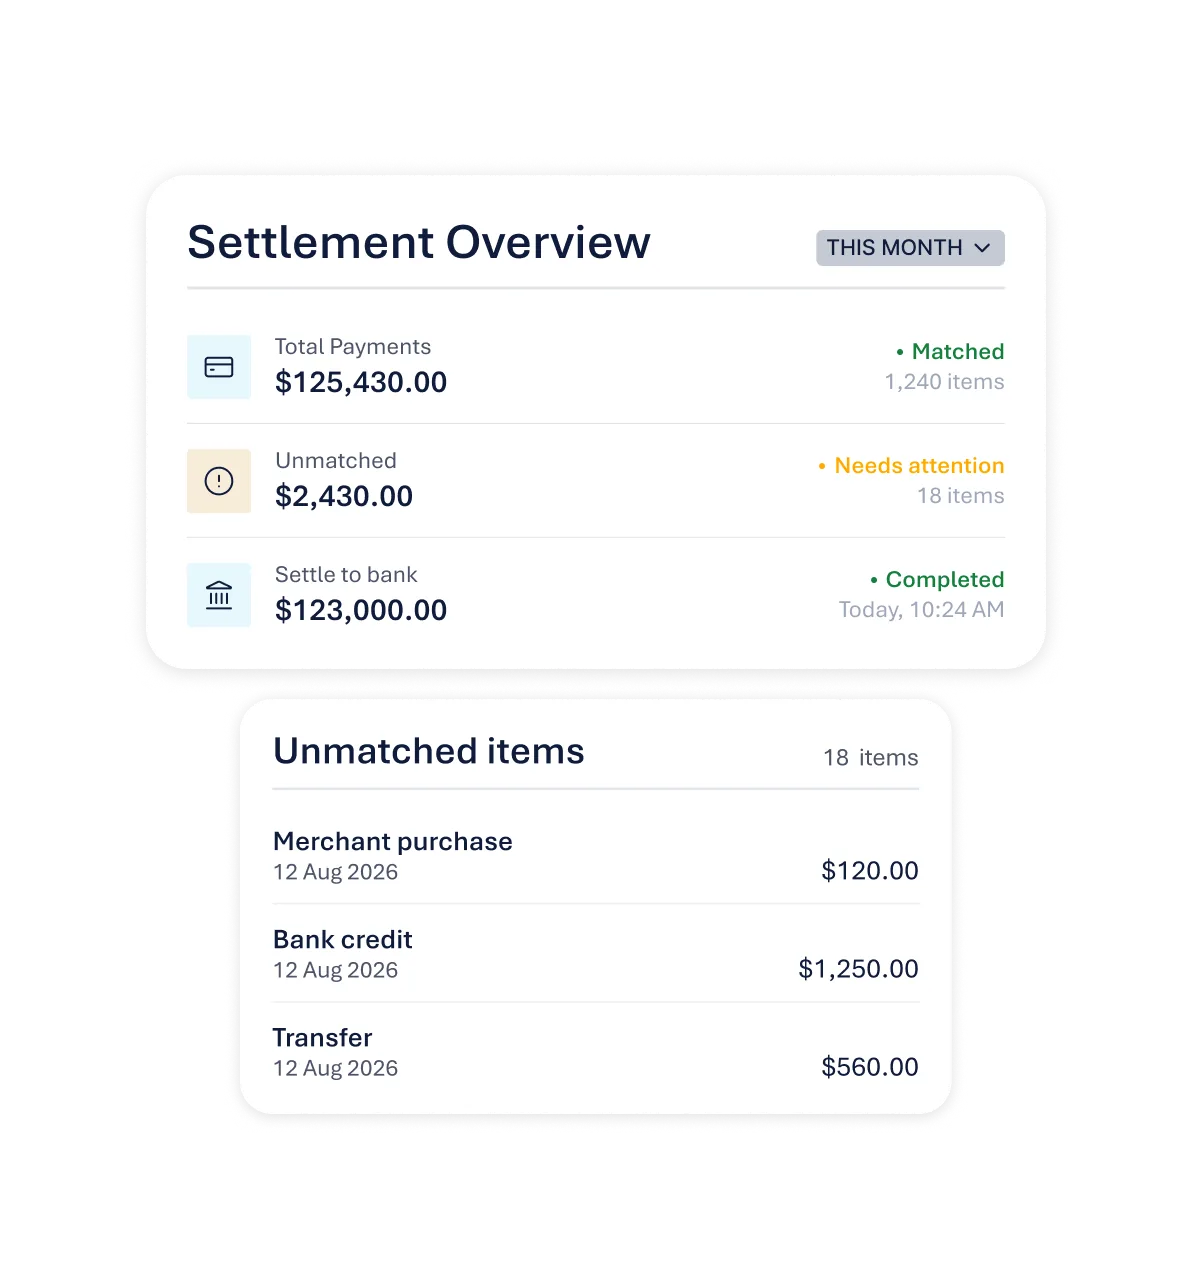
Automate the matching between payment, scheme, bank and platform records so finance teams spend less time chasing differences.
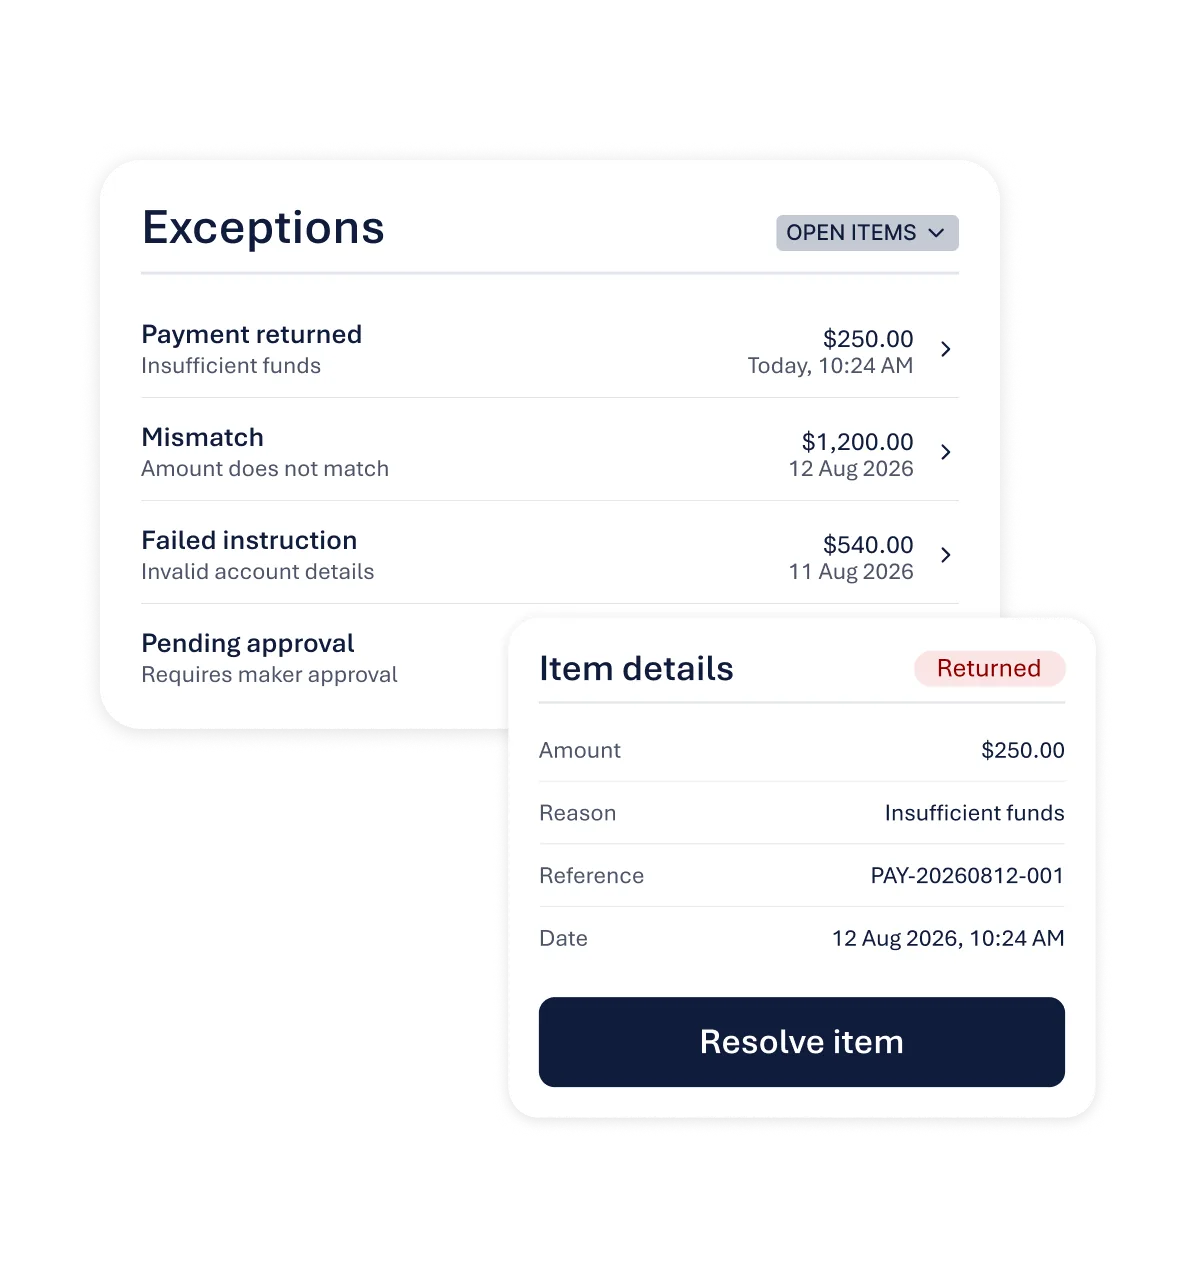
Failed instructions, returned payments and mismatches are part of running payment programs at scale. EML gives teams a structured way to resolve them.
Fees, journals and invoicing outputs come out of the platform in a form finance system can consume.
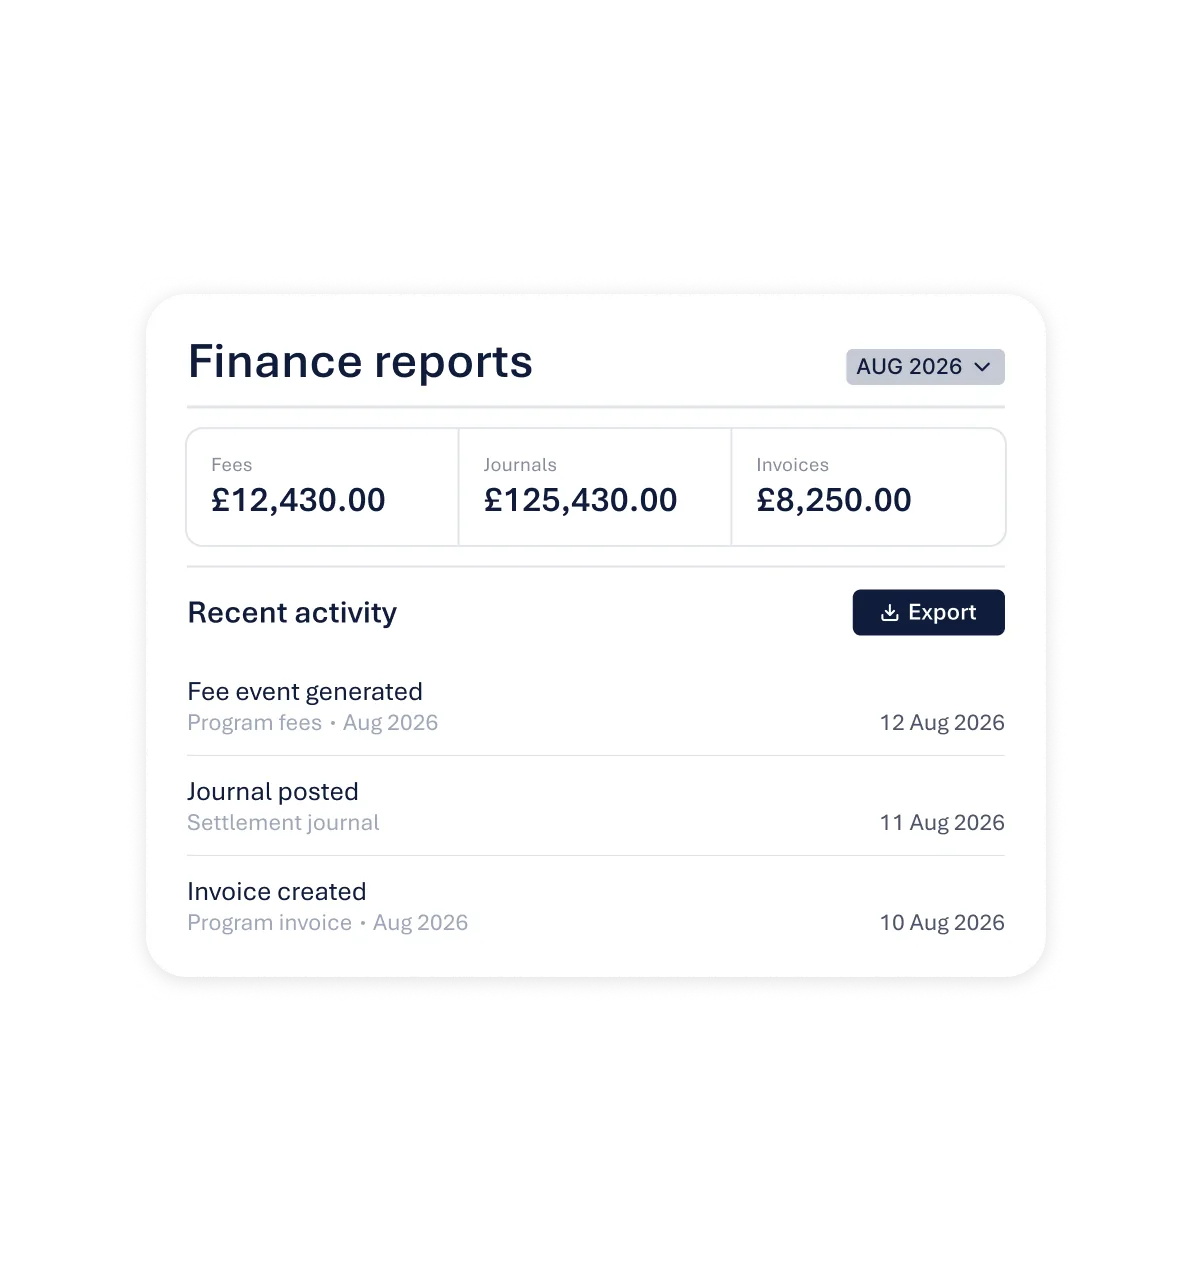
EML Payments gives you flexible ways to launch, integrate and modernise payment programs, with the tools and support to match where you are today.
Choose how you connect. Start with ready-made white label portals and components or integrate directly through APIs and webhooks.
Move onto EML with less disruption. We assess what you have, plan the pathway, and support the migration and the operations that follow.
Program templates, prebuilt components and portals, or direct integration via APIs. Pick the path that matches your needs.
Decide what the card can do before one exists. Currencies, funding model, account structure, spend controls and restrictions.
Choose how money reaches the card. Load it upfront, top it up over time, or hold it centrally and release it only when a transaction is approved.
Virtual in seconds, into Apple Pay and Google Pay, or physical in the post. Branded or generic, one card or a hundred thousand.
When a transaction happens, the platform checks it against your program rules before approving or declining it.
Take control of lifecycle, reporting, reconciliation and settlement, or choose the level of operational support from EML you need.
Across five sectors, EML combines configurable technology, regulatory know-how, proven expertise and end-to-end capability to solve complex payment challenges.

For employers and benefits providers managing pay, expenses, rewards and entitlements for their people.
Salary packaging
Employee rewards
Earned wage access
Expense management

For central and local government teams disbursing funds to people who need them.
Disability payments
Benefits and allowances
Carer disbursements
Emergency and crisis relief
Managed funds

For businesses moving money at scale, deliver funds quickly through flexible, branded payment experiences with built-in controls and limits.
B2B payouts
B2C payouts
Corporate incentives
Lending and credit

For brands, retailers and venues managing gift, loyalty and event programs. Create branded value customers can buy, receive and spend wherever you operate.
Gift cards
Stadiums and events
VIP programs
Loyalty and rewards
Cashback and promotions

For fleet teams managing spend beyond the pump. Fuel, EV charging and everyday mobility spend on one open-loop card.
Fleet & Fuel Expenses
*Use cases vary per region, contact Sales for more information.
In most of our markets you can run under our licences and scheme memberships rather than obtaining your own. United Kingdom: FCA authorised e-money licence. Ireland and Europe: Central Bank of Ireland authorised e-money licence, so you can issue into Europe from an EU authorised entity. Australia: Australian Financial Services Licence. North America: we work through issuing bank partners rather than holding our own licence, which is the standard model in that market.
It depends on how you pay them, not on which platform you use. Money moved onto a card or account inside the platform is available to spend in real time. Money sent out to a bank account moves at the speed of the rail: real time rails such as NPP in Australia and Faster Payments in the UK settle in seconds, while SEPA and ACH follow their own clearing cycles.
Yes, and it is often the reason a program chooses cards over transfers. Value loads to a card or wallet the recipient can spend straight away, so the payout does not depend on bank details being on file or on the recipient passing a bank's own onboarding. This works the same way in every market we operate in.
One platform, one movement model, configured per market. You integrate once rather than rebuilding for each country. Each market brings its own licence, rails and local requirements, so programs are set up per market rather than stretched across them, and cross border movement runs on supported corridors with consistent conversion and posting. Adding a market is a configuration and compliance exercise, not a new build.
Arrangements differ by licence and by banking partner, and we provide the detail your procurement and risk teams need as part of scoping.
Return reasons and timings differ by rail. The handling does not. Failures, returns and mismatches route into the same exception queues with an owner, a state and a resolution record, whichever rail or market they came from, so you run one process rather than a different workaround per country.
Fee events, journals and posting outputs are generated from program activity and fed to finance workflows through supported integrations. One set of outputs regardless of how many markets you run in, so a multi market program does not mean a separate reconciliation process per country.
One partner with the card issuing and processor platform, the licence and the people to launch your program and keep it running as it scales.

Cards, accounts, wallets, money movement, controls and data brought together and configured around your program.

APIs, pre-built components, white label portals and partner integrations. Connect in the way that works for your team.

Issuer, processor and program manager capability in one place, with the licensed infrastructure to run complex and regulated programs end to end.

Security, access controls, data protection, fraud monitoring and sanctions screening protect your program, your users and your money, informed by local regulatory environments.

Live across APAC, Europe, the UK and North America, with teams who understand local rules, schemes and market realities based on decades of experience.
Real experts alongside the technology, from pilot through to live operation. You get a partner, not a ticket number.
Issue, process and project manage cards ad accounts. Move money and manage complex payment flows with real-time intelligence and control, with proven experts behind every transaction.
Create accounts, cards and wallets at scale.
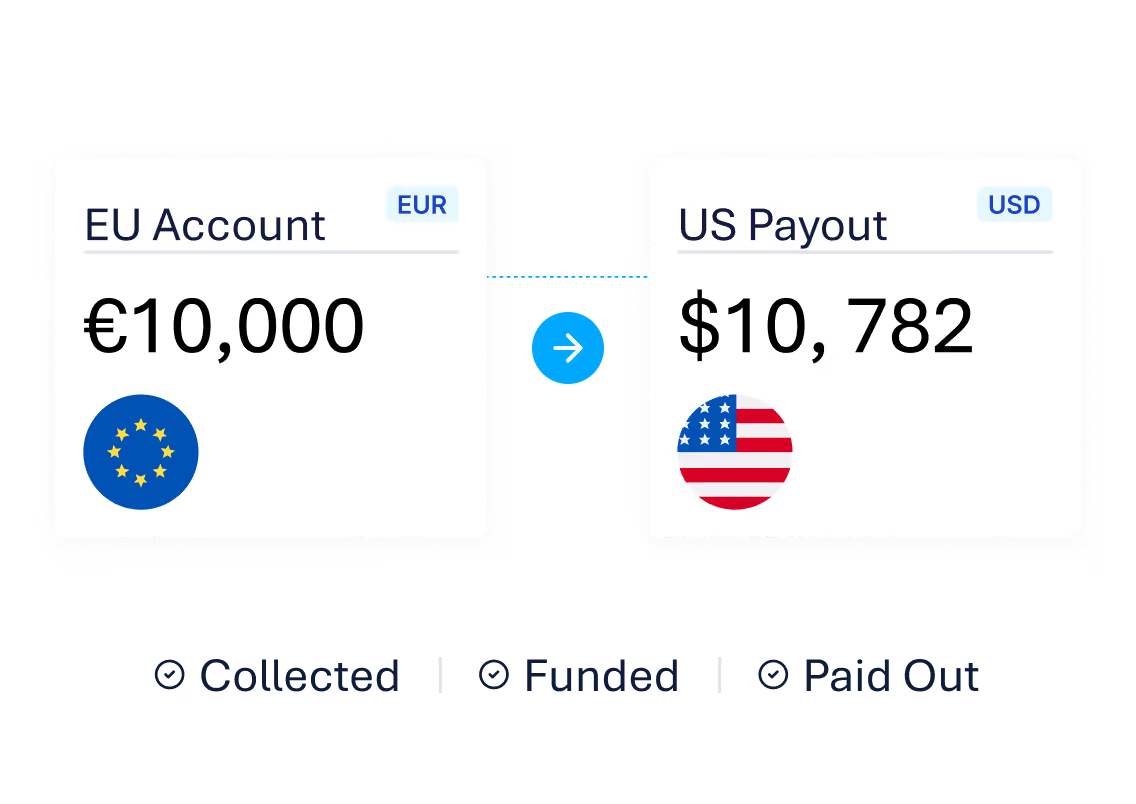
Move money in and out of your program.
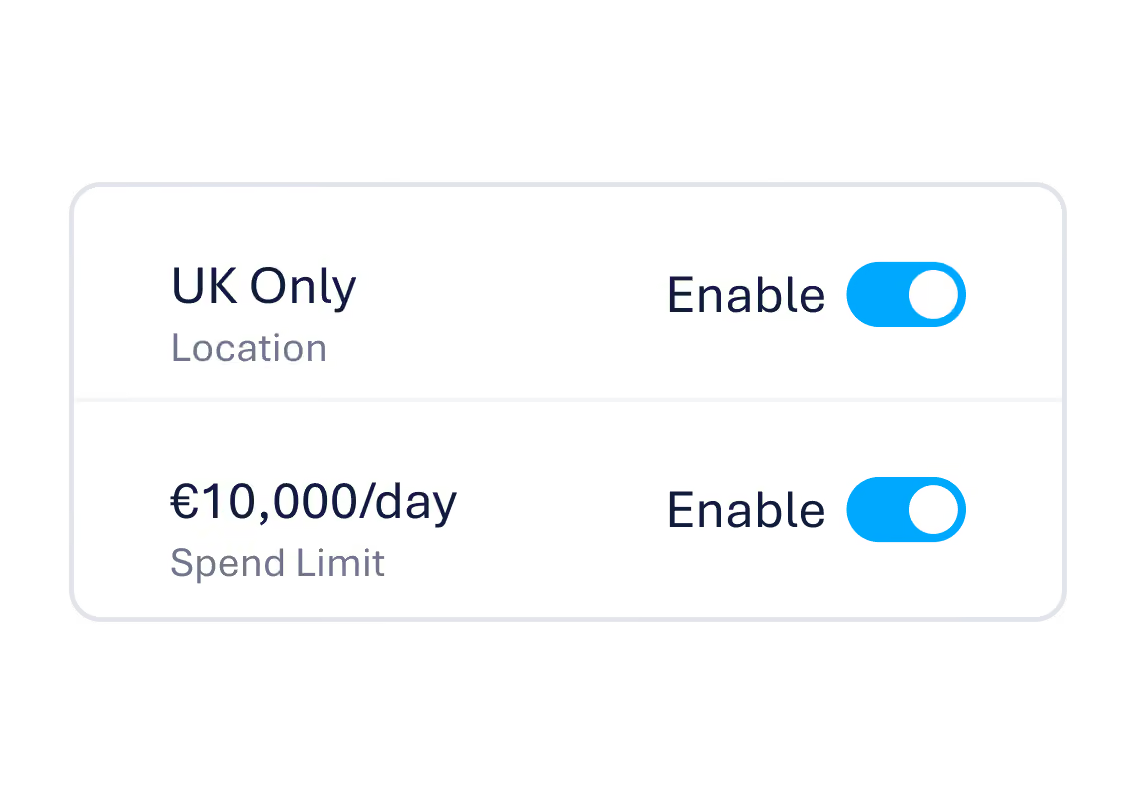
Shape how money behaves in real time.
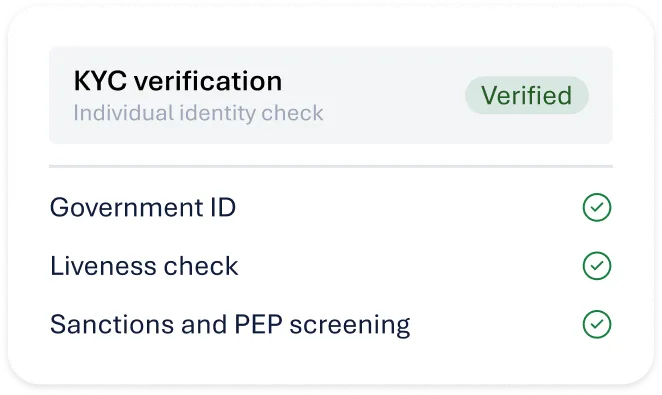
Build trust and protection into every transaction.
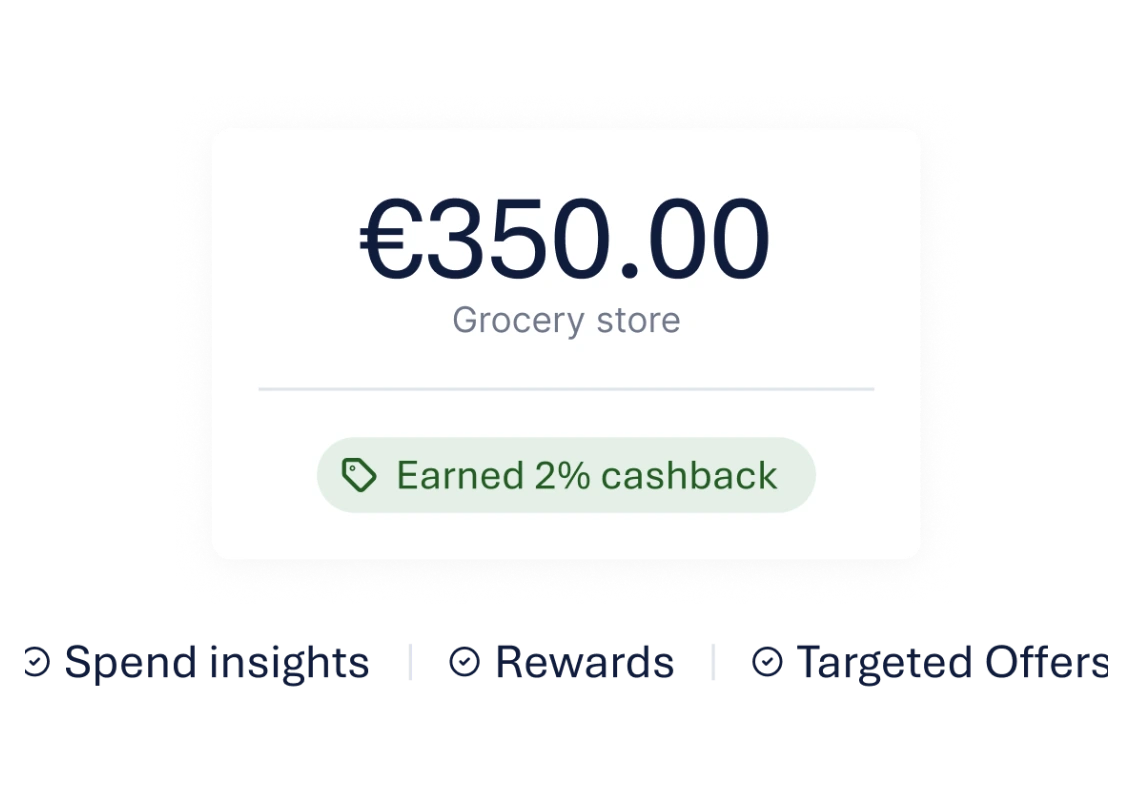
Use insights and incentives to drive growth.
Build with white label portals, pre-built components or direct integration.
Whether you're launching, modernising or scaling, an EML specialist will map the right platform, operating model and next steps to get you there. Let's talk.


